TRENDING
Middle East conflict voids travel insurance, disrupts plans
7 minutes reading View : 88

経済 - 18 May 2026

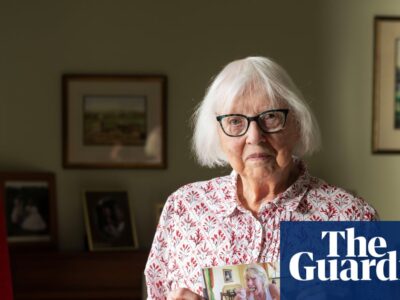
In February, Lottie Cornwall booked a summer trip to Lebanon and looked forward to introducing her boyfriend to her Lebanese extended family.
“My mum’s whole side of the family live there,” she said. “I last saw my grandmother and cousins in 2022. My heritage means everything to me, and this was a chance for my boyfriend to meet my family, and to show him where I come from and why I’m so in love with it.”
But, like many other Britons, the 21-year-old’s plans derailed due to the Iran war.
In March, the Foreign Office changed its advice, warning against travel to parts of Lebanon. When she examined her “comprehensive” travel insurance policy, she found it excluded “any claim due to changes in travel advice.”
The Nottingham Trent University student, who works part-time as a waitress, purchased the flights and insurance via online travel agency Trip.com. The company contacted AJet on her behalf, but the airline, a subsidiary of Turkish Airlines, said standard rules applied, with fees to cancel or change the return trip via Istanbul totaling £673. The original booking cost £782.
“The Foreign, Commonwealth and Development Office (FCDO) is warning British nationals not to travel to Lebanon, and my insurer says my policy is void if I do travel,” Cornwall told Guardian Money. “This exclusion is not made clear at point of sale. I believe consumers are being misled into purchasing premium policies.”
“I assumed if your government is telling you not to go somewhere, the airline would give you a credit or change the booking. We will not make the trip if the advice stays the same and will lose the money.”
Her case highlights the need to check insurance policy details carefully to avoid being caught out.
Some policies would cover some costs resulting from a travel advice change. The trade body Association of British Insurers (ABI) warns that traveling against FCDO advice could invalidate travel insurance.
However, if travel is necessary, such as for a family bereavement, specialist cover is possible but must be arranged before departure.
Currently, fewer policies are available for destinations affected directly or indirectly by the Middle East conflict, including the United Arab Emirates and Cyprus, where some insurers have paused quoting, according to analysts Defaqto.
Defaqto director Stephen Kennedy said: “Travellers should treat insurance as something to check before they book, not after. Availability can change quickly when a destination is affected by conflict, airspace closures or FCDO advice, and some insurers may pause quoting while they reassess the risk.”
“Most standard travel policies are not designed to cover losses arising directly from war or armed conflict,” Kennedy said. “That means travellers should not assume they can cancel because they are worried about travelling, or claim for disruption linked to the conflict, unless their policy clearly says so.”
Travelers seeking policies will likely find less choice, more exclusions, and greater scrutiny around destination and official travel advice. Costs may also rise. The average premium for a trip to Turkey costs 12% more than last year, according to Compare the Market. For the UAE and Saudi Arabia, increases are 22% and 21%, respectively.
If a flight is cancelled, travelers should contact their airline or tour operator, as these entities are responsible for offering refunds, rerouting, or alternative plans, the ABI said.
Those on package holidays have stronger protections under package travel regulations. The travel company must ensure customers receive the holiday they paid for, either by offering an alternative or providing a full or partial refund.
Confused.com’s Tom Vaughan said that if a flight cancels due to a fuel shortage, the airline must provide an alternative flight or refund the cost.
“Some travel policies will cover travellers for disruption to their journey, although this must specifically be included,” Vaughan said. “Certain policies provide cover for unrecoverable costs when a flight is cancelled or delayed after check-in and results in a delay of more than 12 hours.”
Aviva, for example, said its policies contain an exclusion for direct and indirect consequences of war. “This means that claims arising from fuel shortages caused by the war in the Middle East are not covered.”
However, Aviva added: “We wish to support customers where flight cancellations result in them becoming stranded abroad. In this circumstance, we will consider claims on a case-by-case basis if they are unable to recover costs from elsewhere. This includes unrecoverable costs for hotels and excursions and applies regardless of when the policy was bought.”
MoneySavingExpert reviewed 40 travel insurance policies and found “only a few” that would cover financial knock-on effects of a flight cancellation linked to fuel shortages. The list includes Urban Jungle and policies bundled with Lloyds Silver and Halifax Ultimate Reward packaged bank accounts.
Those who organize their own travel itinerary face the highest risk of losing money on prepaid accommodation, car hire, and excursions, said MoneySavingExpert founder Martin Lewis.
“People’s hotel costs, if they book separately, and other knock-on costs, are potentially at risk,” Lewis said. He advises contacting the hotel or car hire company directly if the worst happens. “Once you understand that you have no rights, and they say: ‘We’ll give you a voucher’… you suddenly realise you’re doing well, not badly.”
The mantra is to buy insurance “as soon as you’ve booked,” because cover applies not just for the trip but also for issues before departure.
Gary Murphy, head of travel at Gigasure, said: “Travel insurance is designed to cover the risk to the individual, such as having to cancel due to illness or being made redundant. War is a mass risk and it’s really difficult to price for that … so generally those type of risks are excluded.”
“If you haven’t booked, the best advice is to book a package trip,” Murphy added. “Then, if something happens, the travel provider is liable to refund, replace or reorganise it. If you don’t want to book a package, then book flexible arrangements.”
While travel policy documents can be off-putting, the “insurance product information document” provides a concise overview of what is and is not insured.
Travelers should check that the benefit limit for cancellation or curtailment is high enough to cover the full trip cost, especially for expensive holidays or family travel.
Also examine how the excess applies. About a quarter of policies charge excess on a “per person” basis, while almost two-thirds apply multiple excesses to a single claim, according to Defaqto.
A “per person, per section” excess applies separately for each person and each part of a claim. For example, if a couple claims for stolen luggage and money under this structure, a £50 excess could be applied four times, resulting in a £200 contribution.
However, the main issue now is not price but whether insurance will “be worth the paper it’s written on,” said Jane Hawkes, who runs the consumer advice website Lady Janey.
Hawkes said: “Consumers should look for policies with strong travel disruption and curtailment cover, and check carefully how insurers handle changes in [travel] advice after booking. For most mainstream travellers, established insurers with strong emergency assistance and clearer disruption policies are likely to offer better protection than ultra-budget options.”
When questioned about Cornwall’s predicament, Trip.com told Guardian Money: “Our team reviewed all available information and liaised closely with the relevant travel partner to assess the options available. Based on the current facts, the flight remains operational and the booking does not fall within the scope of the airline’s applicable waiver policy. As a result, any cancellation would need to be processed in line with the fare rules and charges associated with the original booking.”
“The relevant insurance policy documents and terms were made available during the purchase process and sent to the customer by email after purchase. These documents set out the policy terms, including the cover, restrictions and exclusions that apply. We have advised the customer to contact the insurer directly to verify whether the situation qualifies for coverage under their policy terms.”
📝 This article was rewritten with AI assistance based on content from The Guardian.
Related posts




Latest Post